Cameco posts $43 million net earnings in Q3 2026 as Key Lake outage and lower Westinghouse returns weigh on year-over-year results
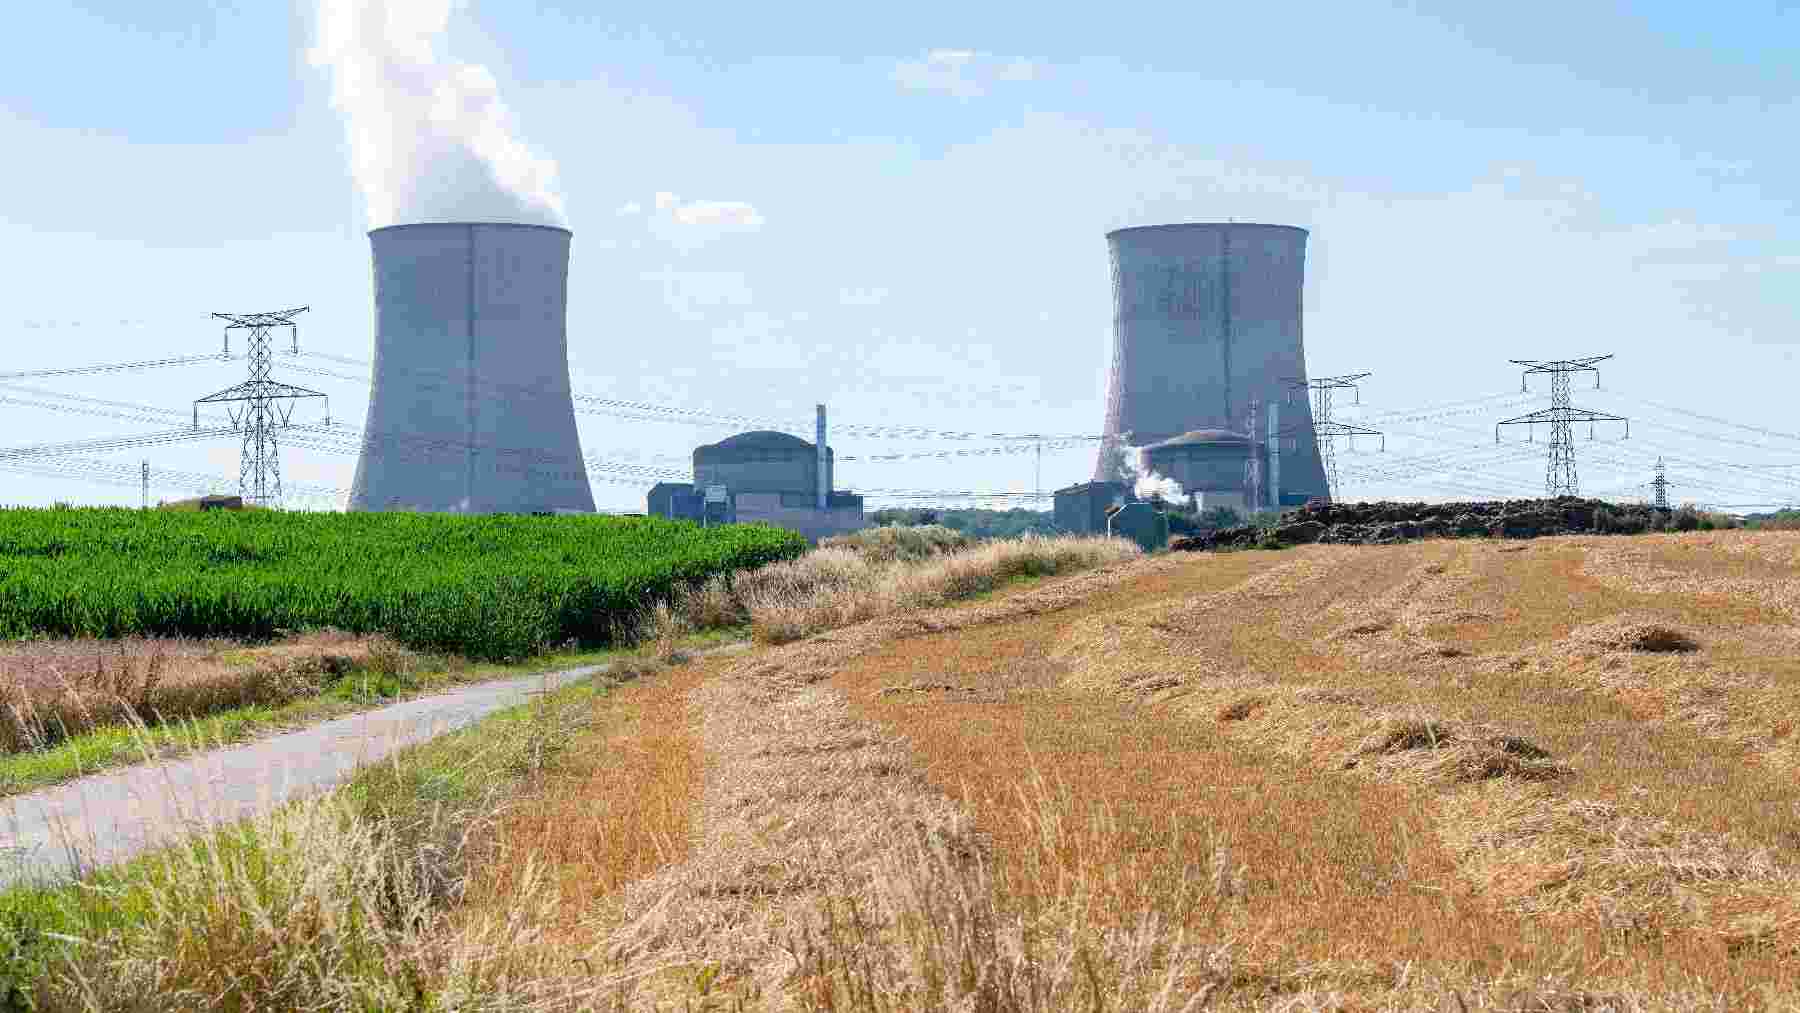
On October 30, 2026, Cameco reported its third-quarter financial results, reporting net earnings of C$43 million (approx. US$31 million) for the quarter and C$199 million (approx. US$143 million) for the first nine months of the year — both below year-ago levels. The uranium producer pointed to two main culprits: a planned but longer-than-usual maintenance shutdown at its Key Lake mill, which squeezed production volumes and drove up costs, and weaker equity earnings from its Westinghouse stake — partly because Westinghouse had received a large one-time payment in 2025 tied to a Czech nuclear project.
Q3 and year-to-date financial results
Cameco’s Q3 numbers carry some nuance. Net earnings of C$43 million (approx. US$31 million) sit alongside an adjusted net loss of C$2 million (approx. US$1.4 million) — a gap that comes down to specific one-time items running through the reported figures. Adjusted EBITDA for the quarter landed at C$267 million (approx. US$192 million).
Pull back to the first nine months of 2026, and things look more solid: C$199 million in net earnings (approx. US$143 million), C$279 million in adjusted net earnings (approx. US$201 million), and C$1.2 billion in adjusted EBITDA (approx. US$864 million). Those year-to-date figures are still trailing 2025’s comparable period, driven by lower Westinghouse equity earnings, fewer uranium sales volumes, and higher unit costs — partially offset by stronger average realized prices.
JV Inkai remains on track to produce 10.4 million pounds of U3O8 on a 100% basis in 2026, with Cameco’s purchase allocation expected at 4.2 million pounds.
The balance sheet remains healthy. As of September 30, 2026, Cameco held C$860 million in cash and cash equivalents (approx. US$619 million), carried C$1.0 billion in total debt (approx. US$720 million), and kept a C$1.0 billion revolving credit facility completely untouched (approx. US$720 million).
Causes of the year-over-year decline: Key Lake and Westinghouse
Two factors do most of the work in explaining the gap versus 2025.
First, Key Lake. The annual maintenance shutdown started during Q3 2026 but ran longer than planned. Cameco used the window to install new infrastructure and tackle major equipment repairs — work that compressed production volumes and pushed unit costs higher for the quarter.
Then there’s Westinghouse. Cameco’s share of Westinghouse’s net loss came to C$24 million in Q3 2026 (approx. US$17 million), which is actually an improvement from a C$32 million loss in Q3 2025 (approx. US$23 million), but still a drag. The year-to-date comparison is starker: a C$80 million net loss through nine months of 2026 (approx. US$58 million), versus C$32 million in net earnings over the same stretch in 2025 (approx. US$23 million).
Most of that swing traces back to a single 2025 event — a payment Westinghouse received tied to the Dukovany nuclear project in the Czech Republic, one that added roughly US$170 million to Cameco’s share of Westinghouse’s second-quarter 2025 revenue. Strip that out, and the year-over-year comparison looks considerably less dramatic. Inflationary pressure and broader market volatility added further headwinds on top.
Segment performance: Uranium, fuel services, and Westinghouse
Breaking things down by segment shows where the business is holding up and where pressure is concentrated.
In uranium, Q3 earnings before taxes reached C$175 million (approx. US$126 million), with adjusted EBITDA of C$179 million (approx. US$129 million). For the first nine months, adjusted EBITDA came in at C$855 million (approx. US$616 million). JV Inkai remains on track to produce 10.4 million pounds of U3O8 on a 100% basis in 2026, with Cameco’s purchase allocation expected at 4.2 million pounds.
Fuel Services posted Q3 earnings before taxes of C$13 million (approx. US$9.4 million) and adjusted EBITDA of C$24 million (approx. US$17.3 million), with year-to-date adjusted EBITDA reaching C$120 million (approx. US$86.4 million). Annual fuel services production is still expected to land between 13 and 14 million kgU.
The Westinghouse adjusted EBITDA picture is more encouraging than the net loss figures suggest. Cameco’s share of Westinghouse’s Q3 adjusted EBITDA was C$143 million (approx. US$103 million) — up from C$124 million in Q3 2025 (approx. US$89 million). Year-to-date, that figure stands at C$427 million (approx. US$307 million), compared to C$569 million in 2025 (approx. US$410 million), with most of the gap traceable to the Dukovany one-time item.
2026 outlook update and operational guidance
As the year winds down, Cameco tightened its guidance ranges across the board.
Uranium production guidance was narrowed to 19.5–20.5 million pounds, from a prior range of 19.5–21.5 million pounds, with the company citing greater certainty in production timing. Sales and delivery volume guidance moved similarly, landing at 29.5–30.5 million pounds from the earlier 29–32 million pound range.
October brought a couple of notable Westinghouse developments. The company announced conditional purchase orders with four Polish suppliers supporting the first AP1000 unit at the Lubiatowo-Kopalino site, and launched a US State Department-funded front-end engineering and design study for an AP1000 reactor at Slovakia’s Jaslovské Bohunice site. Cameco’s board also Cameco’s board also declared a 2026 annual dividend of C$0.24 per common share (approx. US$0.17), payable December 15, 2026, to shareholders of record on November 30.
Nuclear market fundamentals and what’s next for Cameco
Heading into Q4, Cameco’s contract book covers average annual uranium deliveries of over 28 million pounds per year across the next five years, with commitments running above that average through 2028.
In September, the US Department of Commerce and South Korea announced a non-binding framework anticipating up to US$120 billion in Korean investment for up to eight new large-scale US reactors, including six Westinghouse AP1000 units. Definitive agreements are still needed before the deal moves forward.
CEO Tim Gitzel was careful about how he framed the company’s outlook. He noted that Cameco‘s investment thesis doesn’t rest on any single demand driver — pointing instead to the existing reactor fleet, life extensions, restarts, new-build commitments, and energy-security priorities as the durable underpinnings of long-term demand.
On the leadership front, Leah Hipperson will become CFO effective January 1, 2027. Heidi Shockey will serve as executive director of finance until retiring on March 31, 2027 — a planned transition Cameco described as consistent with its succession planning approach.
Kelly is an experienced writer with 15 years of experience exploring the big stories that shape our world, from tech breakthroughs and space exploration to climate, energy, and the fascinating quirks of science. She has a talent for turning complex ideas into sharp, memorable insights that stay with readers long after they’ve finished reading.
